The Highest Offer Isn’t Always the Best Offer
An extra $10,000 looks great. Until you read the next page.
When an offer comes in on your home, your eyes probably go straight to the price. Fair enough. That number matters.
But it is not the whole deal.
The credits a buyer requests, the conditions they include, and the day they want the keys can change what that offer means for your move. Before mentally spending the difference, take a breath and compare the complete package.
For Utah sellers, the goal is not simply the biggest number on paper. It is the strongest combination of proceeds, terms, and timing for your situation.
1. Compare what you keep, not just what they offer
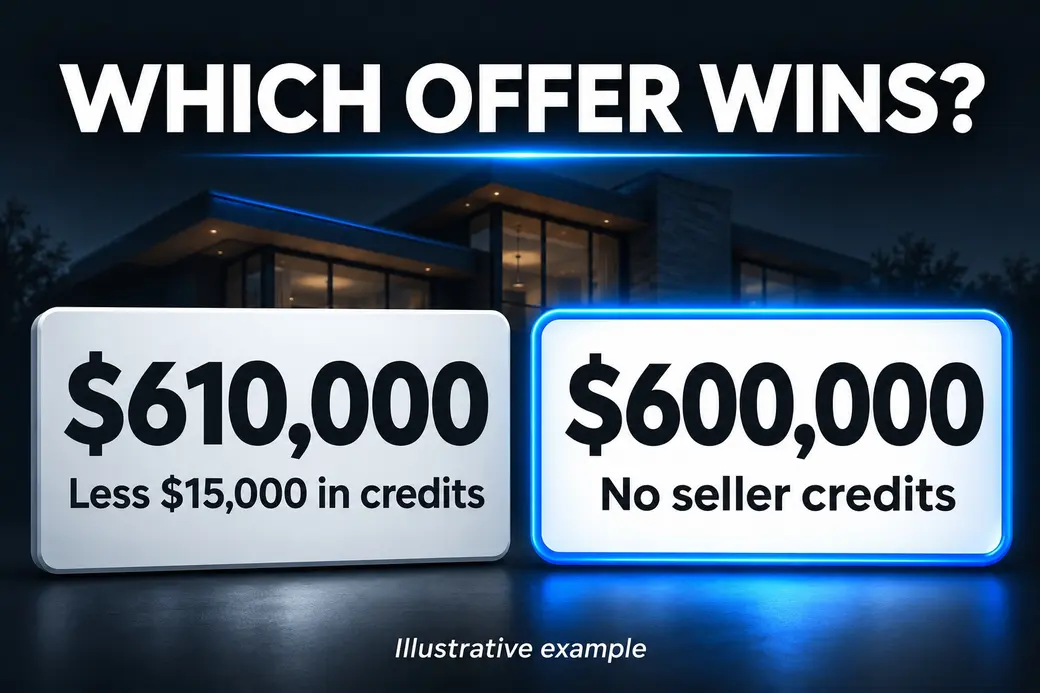
Here is a hypothetical example:
- Offer A: $610,000 with $15,000 in requested seller credits.
- Offer B: $600,000 with no requested seller credits.
Subtract only those credits, and you get $595,000 for Offer A and $600,000 for Offer B. The lower headline price is $5,000 ahead on that limited comparison.
These are not final seller proceeds. Mortgage payoff, brokerage compensation, title charges, taxes, repairs, and other costs still need to be considered. Credit availability also depends on applicable financing requirements.
Ask your agent for an estimated seller net comparison using the same assumptions for every offer. Include requested repairs, items you would leave behind, and any other seller expenses in the terms.
A credit request is not automatically a bad thing. It just belongs in the math.
2. Look beyond the financing label
“Cash” gets attention. “Preapproved” sounds reassuring. Neither word answers every question.
For a financed offer, have your agent coordinate with the buyer's agent and lender, with appropriate permission, to clarify what has been verified, what conditions remain, and whether the proposed timeline is realistic. A preapproval is not a guarantee of final loan approval.
Do not assume a buyer is less capable because they are using FHA, VA, or another loan program. Compare documented readiness and the actual requirements affecting the transaction, not stereotypes about loan types.
For cash, review current proof of available funds and the contract terms. Does the purchase depend on selling another property? Are inspection or appraisal conditions still included?
Cash can remove a financing step. It does not automatically make an offer the best one.
3. Read the conditions behind the price
Contingencies are contract conditions that can affect whether a sale moves forward. They are not automatically warning signs, but they deserve more attention than a quick glance.
Review inspection or due diligence terms, financing and appraisal conditions, and any requirement for the buyer to sell another home.
Ask: What still has to happen? By when? What does the contract allow if it does not happen?
Appraisal risk deserves its own conversation. A buyer offering more does not make the home appraise for more. If the appraisal is below the agreed price, the next steps depend on the financing and contract terms.
If an offer includes a promise to cover an appraisal shortfall, review the written amount, limits, and evidence of available funds. An enthusiastic promise and a documented plan are different things.
4. Make the calendar part of the comparison
The fastest closing is not always the most useful closing.
Maybe your next place will not be ready yet. Maybe you need sale proceeds before completing your next purchase. Moving twice, storing furniture, or arranging temporary housing can affect both your budget and your patience.
Compare the proposed closing schedule with the possession terms. Do not assume signing documents means handing over the keys that afternoon.
Any arrangement to stay after closing needs clear written terms and appropriate professional review. A friendly “we can work that out” is not a moving plan.
5. Put earnest money in perspective
A larger earnest money deposit can signal commitment. It is not extra purchase money on top of the price, and it is not automatically yours if the sale falls apart.
Whether funds are returned or retained depends on the contract, applicable law, and the circumstances. Review the deposit alongside the contingencies, not as a substitute for understanding them. Ask legal counsel about contract rights or disputes.
Choose the offer that fits your move
Before deciding, put each offer on the same comparison sheet: estimated net proceeds, verified funding, remaining conditions, earnest money terms, closing, and possession.
Then weigh those facts against your priorities. Keep the decision focused on objective transaction terms, not buyer photos, personal stories, protected characteristics, or assumptions about who would fit the neighborhood. Apply the same criteria consistently.
The highest offer might still win. It should win because the full package makes sense, not because page one was exciting.
Thinking about selling your Utah home? Utah's Realty Team can help you build a selling plan and compare offers around what matters to your move. No pressure to list before you are ready.
General information only, not legal, tax, or lending advice. Consult qualified professionals for your circumstances. No sale outcome is guaranteed. Equal Housing Opportunity.
Recent Posts
GET MORE INFORMATION